 Monday, November 02, 2026
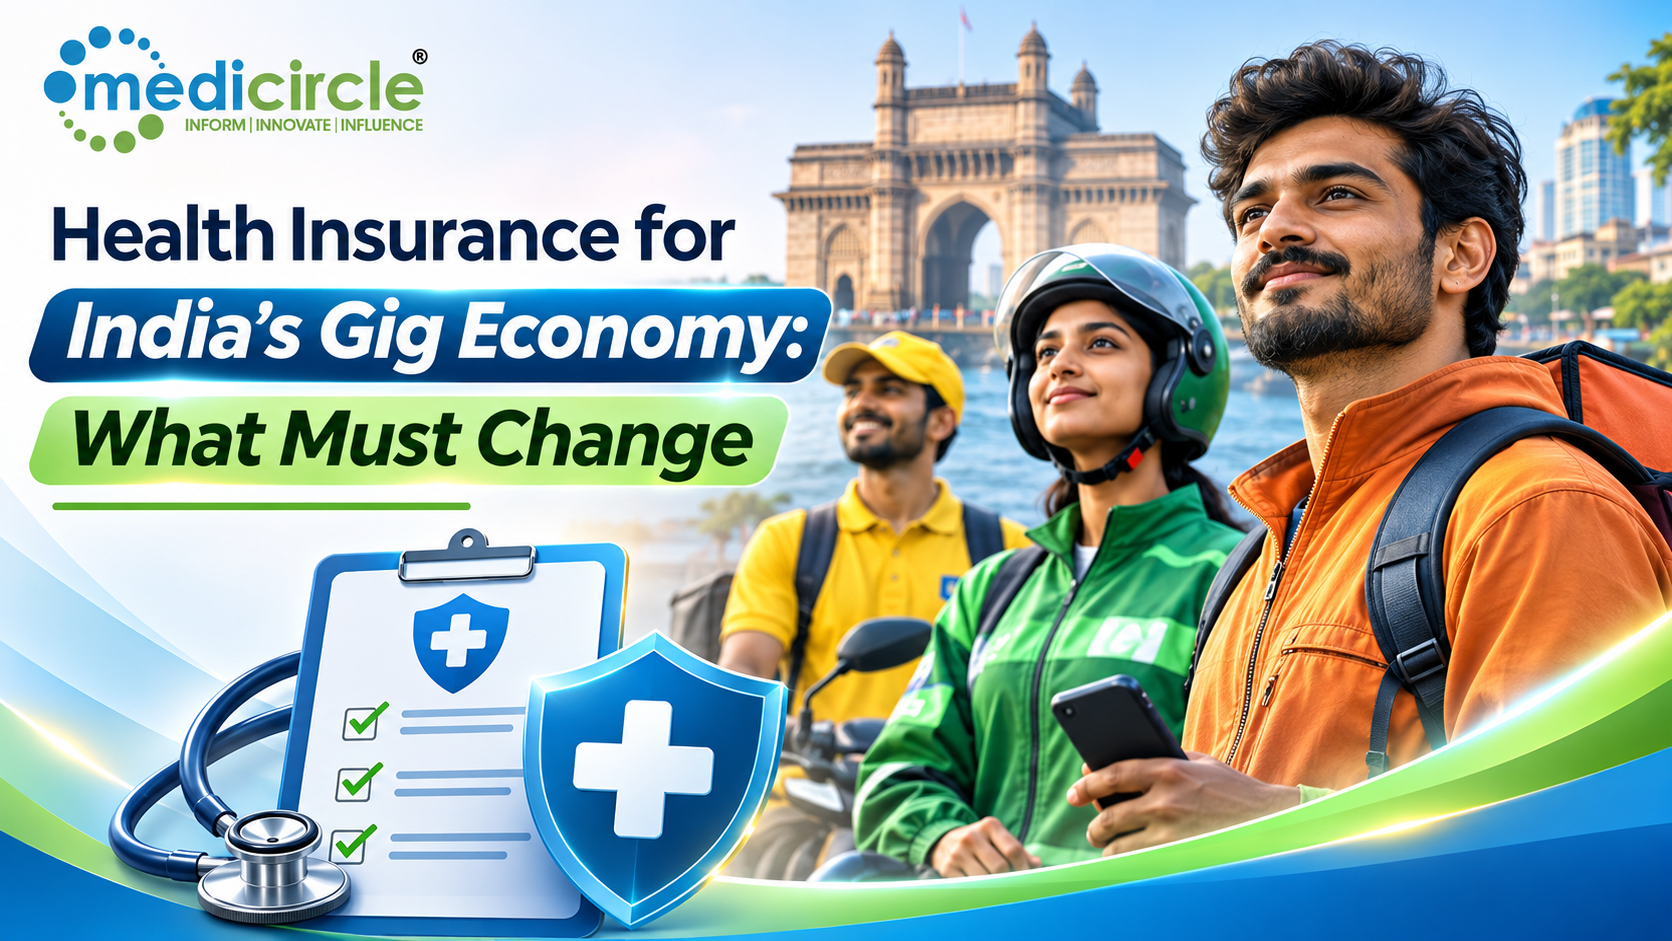
 India's gig economy is expanding rapidly, but millions of platform workers remain without adequate health insurance, exposing them to severe financial and health risks that urgently demand structural policy reform.

Introduction
India's gig economy has grown at a speed that few policy frameworks have been able to match. From delivery riders navigating busy city streets to freelance designers working from Tier 2 towns, millions of Indians now earn their living outside the boundaries of traditional employment. According to estimates from NITI Aayog, India had approximately 7.7 million gig workers in 2020, and this number is projected to reach 23.5 million by 2029 to 2030. These workers power some of the country's most recognizable platforms and service brands, yet they remain almost entirely unprotected when it comes to health coverage.
The absence of robust health insurance for gig workers is not a minor administrative gap. It is a structural flaw in how India thinks about work, welfare, and healthcare access. When a platform delivery executive fractures his wrist in a road accident, or when a freelance content creator faces a prolonged illness, there is no employer-sponsored insurance to fall back on. The financial consequences can be devastating, and in a country where out-of-pocket healthcare spending remains among the highest in the world, this is a crisis hiding in plain sight.
Understanding what health insurance options exist for gig workers, what is failing, and what meaningful reform would look like is urgently relevant as India moves toward a future where flexible work will only become more prevalent.
The Current State of Gig Worker Health Coverage in India
The majority of gig workers in India fall into a definitional gray zone. They are not permanent employees, so they do not qualify for the Employees' State Insurance (ESI) scheme or employer-paid group health insurance. They are also not technically self-employed business owners, which makes navigating individual insurance products an inconsistent and expensive experience.
Some platform companies do offer limited accident insurance or basic hospitalization cover to their active workers. However, these policies are often thin in scope, restricted to on-duty incidents, and tied to platform activity thresholds. A gig worker who slows down for a few weeks due to illness may find that their insurance lapses precisely when they need it most.
Government schemes such as Ayushman Bharat Pradhan Mantri Jan Arogya Yojana (PM-JAY) offer coverage to economically vulnerable families, and some gig workers may qualify based on income criteria. However, the scheme is not specifically designed around the needs of platform workers, and awareness about eligibility among this population remains limited. State-level schemes vary significantly, creating unequal outcomes depending on where a worker happens to live and work.
The broader picture is that health insurance coverage for gig workers in India is fragmented, insufficient, and largely reactive rather than systemic.
Why Gig Workers Are Structurally Excluded from Health Protection
To understand the problem properly, it helps to look at the structural reasons why gig workers fall through the cracks of India's existing health insurance architecture.
India's formal health insurance ecosystem has historically been built around two pillars: employer-sponsored coverage for salaried employees, and individual or family floater plans purchased voluntarily. Gig workers fit neatly into neither category.
Employer-sponsored plans require a recognized employment relationship. Because gig workers are classified as independent contractors by most platforms, the employer obligation to contribute to health coverage simply does not apply. This classification is commercially convenient for platforms, but it shifts the entire burden of risk onto individual workers who often earn irregular and modest incomes.
Individual health insurance plans, on the other hand, present their own set of barriers. Premiums for comprehensive individual plans can range from Rs 8,000 to Rs 25,000 or more per year depending on age, sum insured, and pre-existing conditions. For a delivery worker earning Rs 15,000 to Rs 20,000 per month with no income certainty from one week to the next, this is a significant and often unaffordable commitment. Waiting periods for pre-existing diseases, complicated documentation requirements, and low insurance literacy compound the challenge further.
There is also a data problem. The gig workforce in India is not comprehensively counted or formally registered in a centralized system. Without reliable data on who these workers are, where they live, what they earn, and what their health risks look like, designing targeted insurance products for this segment has remained a secondary priority for both insurers and policymakers.
The Health Risks Gig Workers Face
The health risks faced by gig workers are real, recurring, and often occupationally specific. Yet they are systematically underrecognized in India's public health discourse.
Delivery workers and ride-hailing drivers face elevated risks of road accidents, musculoskeletal injuries, and respiratory problems due to prolonged outdoor exposure. The physical demands of the job, combined with irregular working hours, irregular meals, and inadequate rest, create conditions that significantly increase the risk of lifestyle-related illnesses over time.
Freelancers and digital gig workers, while not exposed to the same physical risks, face a different set of concerns. Sedentary work patterns, screen fatigue, irregular sleep, and income-related psychological stress are associated with conditions including hypertension, back pain, and anxiety. Because these workers have no structured workplace wellness programs or access to employer-facilitated preventive care, minor health issues tend to be ignored until they become serious.
Women gig workers face additional vulnerabilities. Maternal health expenses, reproductive healthcare needs, and the social pressure to manage household responsibilities while maintaining gig income create compounded financial and health risks that existing insurance frameworks largely ignore.
The cumulative effect is a workforce that is both highly economically active and highly health-vulnerable, with almost no institutional protection against the financial shock of illness or injury.
What Needs to Change: Policy and Industry Reforms
The conversation about health insurance for India's gig economy cannot remain at the level of awareness alone. It requires concrete, coordinated action from policymakers, platform companies, the insurance industry, and civil society.
Formal Recognition of Gig Workers as a Distinct CategoryThe first and most foundational change required is legal and definitional. India needs a clear legislative framework that recognizes gig and platform workers as a distinct category of workers with specific rights and entitlements, including access to social security and health coverage. The Code on Social Security, 2020 does create provisions for gig and platform workers and mandates that the central and state governments may frame welfare schemes for them. However, implementation has been slow, and the scope of mandated benefits remains narrow. Translating this legal recognition into enforceable, universal health coverage obligations is the critical next step.
Platform Contribution to Health InsuranceThere is a strong case for requiring platform companies to contribute to the health insurance premiums of workers who depend on them for a significant portion of their income. A proportional contribution model, where platforms contribute to a pooled health fund based on the number of active workers and the volume of earnings facilitated, would distribute the cost equitably without imposing the full burden on either workers or the state. Some international models, including legislative developments in the European Union around platform worker classification, offer useful reference points for Indian policymakers.
Flexible, Portable Insurance ProductsIndia's insurance industry needs to develop products specifically designed for irregular income earners. This means:
- Monthly or quarterly premium payment options instead of annual lump sum payments
- Portable coverage that follows the worker across platforms and income sources
- Simplified enrollment and claims processes accessible through mobile phones
- Coverage that includes outpatient care, preventive health checks, and mental health support, not just hospitalization
The Insurance Regulatory and Development Authority of India (IRDAI) has taken steps in recent years to encourage microinsurance and expand health insurance penetration. Building on this foundation with gig-specific product mandates or incentives for insurers who develop and distribute affordable gig worker plans would be a meaningful advance.
Integration with Existing Government SchemesRather than building an entirely new architecture from scratch, India could consider expanding the eligibility and scope of existing schemes like Ayushman Bharat PM-JAY to explicitly include verified gig workers, regardless of income bracket, given the income volatility and occupational health risks specific to this population. The Ayushman Bharat Digital Mission (ABDM) infrastructure, which is building a national digital health ecosystem, offers a ready technological foundation for tracking gig worker enrollment, issuing digital health IDs, and streamlining insurance claims.
Employer and Industry AccountabilityPlatform companies have benefited enormously from the labor of gig workers while externalizing the costs and risks of that labor. Voluntary corporate social responsibility initiatives and token accident insurance policies are insufficient responses to what is a structural equity problem. Regulatory accountability, including annual disclosure requirements for platforms about the health coverage they provide or facilitate for workers, would create meaningful incentives for improvement.
The Role of Awareness and Financial Literacy
Policy reform is necessary but not sufficient. A significant proportion of gig workers in India are either unaware of the insurance options available to them or are skeptical about the claims process and actual utility of insurance products. This reflects a broader financial literacy gap that affects large sections of India's informal and semi-formal workforce.
Healthcare communication platforms, worker collectives, trade associations, and civil society organizations have an important role to play in building gig worker awareness about insurance options, government scheme eligibility, preventive health practices, and the financial importance of health coverage. Digital-first approaches, including short video content in regional languages and WhatsApp-based information campaigns, are likely to be more effective than conventional outreach given how this population consumes information.
Platforms like Medicircle, which are dedicated to making healthcare knowledge accessible and trustworthy, can contribute meaningfully to this awareness effort by providing credible, readable information tailored to the healthcare and financial health needs of India's working population.
Conclusion
India's gig economy is not a passing trend. It is a structural feature of how work is being reorganized in the twenty-first century, and its scale will only grow in the years ahead. Leaving 23 million or more workers without adequate health insurance is not just a welfare failure. It is an economic vulnerability for millions of families and a long-term public health liability for the country as a whole.
The changes needed are clear, even if they are not simple. Legal recognition of gig workers must translate into enforceable protections. Platform companies must share the cost of the risks they currently outsource to workers. The insurance industry must innovate toward flexible, affordable, and genuinely useful products. And government schemes must be designed to reach those who are most exposed to health and income risk, not just those who are easiest to enroll.
India has the regulatory infrastructure, the digital health ecosystem, and the policy momentum to make meaningful progress on this issue. What is needed now is the political will and industry commitment to act before the gap between gig work and health protection becomes an irreversible social crisis.
Frequently Asked Questions
Q1: Are gig workers in India eligible for Ayushman Bharat PM-JAY health coverage?
Gig workers may be eligible for Ayushman Bharat PM-JAY if they meet the scheme's income and socioeconomic criteria. However, the scheme is not specifically designed for platform or gig workers, and eligibility verification can be inconsistent. Gig workers are encouraged to check their eligibility through the official PM-JAY portal or a nearby Common Service Centre.
Q2: Do platform companies in India provide health insurance to their gig workers?
Some platform companies offer limited accident insurance or basic hospitalization cover to active workers. However, these benefits are typically minimal, tied to on-duty activity, and do not provide comprehensive health coverage. There is currently no legal mandate in India requiring platforms to provide full health insurance to gig workers.
Q3: What is the Code on Social Security, 2020, and how does it affect gig workers?
The Code on Social Security, 2020 is a central legislation that consolidates multiple labor laws and includes provisions for gig and platform workers for the first time in Indian law. It allows the government to frame welfare schemes covering health, life, disability, and other benefits for this workforce. However, detailed implementation rules and specific schemes under this code are still being developed and rolled out by state governments.
Q4: What kind of health insurance products are best suited for gig workers in India?
Gig workers benefit most from health insurance products that offer flexible premium payment options, such as monthly or quarterly plans, simple mobile-based enrollment and claims, portable coverage across multiple platforms or income sources, and inclusion of outpatient and preventive care benefits alongside hospitalization. Microinsurance products and group plans offered through worker associations or platform aggregators are also worth exploring.
Q5: How can gig workers in India improve their health and financial protection in the absence of employer coverage?
Gig workers can take several steps to strengthen their health security. They can explore individual or family floater health insurance plans from licensed insurers, check eligibility for government schemes such as PM-JAY or state-level insurance programs, join worker collectives or unions that may offer group insurance benefits, and prioritize preventive health practices to reduce the long-term risk of serious illness. Consulting a certified insurance advisor who understands the needs of self-employed and gig workers is also recommended.
Resources
- NITI Aayog: India's Booming Gig and Platform Economy (2022 Report on gig workforce size and projections in India)
- Ministry of Labour and Employment, Government of India: Code on Social Security, 2020 (official legislation covering gig and platform worker provisions)
- Insurance Regulatory and Development Authority of India (IRDAI): Guidelines and circulars on microinsurance and health insurance product frameworks
- Ayushman Bharat Digital Mission (ABDM): National digital health ecosystem framework and health ID infrastructure details
- World Health Organization (WHO) India Country Office: Reports on out-of-pocket health expenditure and universal health coverage progress in India
Interlinking Keywords
Health insurance for gig workers India, gig economy workers health coverage, Ayushman Bharat PM-JAY eligibility, Code on Social Security 2020 gig workers, platform worker insurance India, freelancer health insurance India, unorganized sector health benefits, IRDAI microinsurance products, out-of-pocket healthcare India, ABDM digital health ID
Last reviewed by:
Dr. Manthan Tripathi, Medicircle Editorial and Medical Advisory Team on 31, October 2026.
Disclaimer
This article is intended for general informational and awareness purposes only. It does not constitute legal, financial, or medical advice. Readers are advised to consult a certified insurance advisor, legal professional, or healthcare provider before making decisions related to health insurance, government scheme eligibility, or medical care. Policy details and scheme eligibility criteria may change over time. Always refer to official government and regulatory sources for the most current information.
-23-300x250.png)